38% of recent Canadian home buyers used a mortgage broker in 2026, up from 32% the year before — and 48% among first-time buyers, a five-year high.
On July 24, Mortgage Professionals Canada released its 2026 Consumer Research Report, and it’s the kind of number that’s worth pinning above your desk. Broker channel share climbed six percentage points in a single year, to 38%. Among first-time buyers, it jumped ten points, to 48%. If it feels like more of your new business lately is coming from people who never set foot in a bank branch, the data agrees with you.
The research, fielded by Bond Brand Loyalty across nearly 2,000 Canadians in seven cities this past February, also found that client satisfaction is at a multi-year high: 83% of broker clients said they’d recommend their broker to a friend or family member, and 72% said they’d use a broker again for their next mortgage. That’s not a channel people are settling for. It’s one they’re actively choosing.
Why the number is moving
The more interesting story is underneath the headline. Best rate is still the top reason people cite for using a broker, but that reason is actually losing ground: it dropped from 59% to 54% year over year. What’s picking up the slack tells you something about what clients want:
• Help understanding their options and the mortgage process: 31%
• Getting multiple quotes to compare: 33%
• A recommendation on which lender to deal with: 26%, up 10 points
• Better service overall: 28%, up 12 points
MPC president Lauren van den Berg summed up the shift by pointing out that mortgage decisions have become more layered, covering rate, lender choice and long-term affordability all at once, which makes professional advice more valuable than it used to be. In other words, clients aren’t just hiring you to find them a number anymore. They’re hiring you to make sense of a more complicated decision, and that’s a much stickier reason to come back next time.
The bigger opportunity sitting behind that number
Here’s where it gets practical. 2026 is on track to be the largest mortgage renewal year in Canadian history, with roughly 1.2 million mortgages coming up for maturity. Historically, a wave like that has been a mixed bag for brokers: plenty of client contact points, but also plenty of clients who assume switching lenders means requalifying from scratch at a higher stress-tested rate, and who talk themselves out of shopping around as a result.
That assumption is now out of date. Since November 21, 2024, OSFI’s Guideline B-20 has exempted straight switches, meaning a renewal where the loan amount and amortization stay the same, from the mortgage stress test for uninsured mortgages. That covers roughly 70% of Canadian mortgages. Practically, it means a client renewing can move to a new lender at that lender’s actual contract rate, without needing to qualify at contract-plus-2% or the 5.25% floor, whichever is higher. Staying with their current lender at renewal has never required a fresh stress test either, so for most straight-switch clients the qualification friction that used to make “just stay put” feel like the safe choice has largely disappeared.
There are still real limits worth knowing cold before you have this conversation: anyone increasing their loan amount, extending their amortization, refinancing to pull out equity, or moving to a lender outside the federally regulated space still faces the full stress test. But for the plain-vanilla renewal, and there are a lot of those in a 1.2-million-mortgage year, the case for shopping the client’s renewal has rarely been this clean.
Turning this into pipeline
A few ways to put this to work before the renewal letters start landing in your clients’ inboxes, typically 120 to 180 days ahead of maturity:
• Segment your database by maturity date now, and build a simple outreach sequence around it: an email around the 150-day mark, a call at 120 days, and a market comparison at 90 days, well ahead of when the client’s current lender reaches out.
• Lead with the exemption, not the rate. A line like “you don’t need to prove anything new to shop your renewal, let’s just see what’s out there” removes the objection most clients are quietly sitting on.
• Widen the conversation to include credit unions and alternative lenders where they fit. CMHC’s own data shows credit union mortgage originations grew 28% year over year (to $23.6 billion in Q3 2025, from $18.4 billion in Q3 2024), outpacing the chartered banks, and driven specifically by switches and purchases. If your panel leans heavily toward the big banks, it may be worth actively building out those relationships.
• Use the current market as useful backdrop, not a sales pitch. CREA’s July data showed national home sales climbing for a fourth straight month, with the sales-to-new-listings ratio at 51.3%, closing in on the long-run balanced-market average of 54.7%. It’s a steady, sensible market, not a frenzy and not a stall, which makes it an easy thing to mention in a renewal or purchase conversation without overselling.
• Tighten up your submission files. A renewal client who’s shopping around for the first time in years often has outdated paperwork on hand; a quick checklist for income docs, down payment history and property documents up front will save you the back-and-forth that slows a deal down and tests a client’s patience.
The bottom line
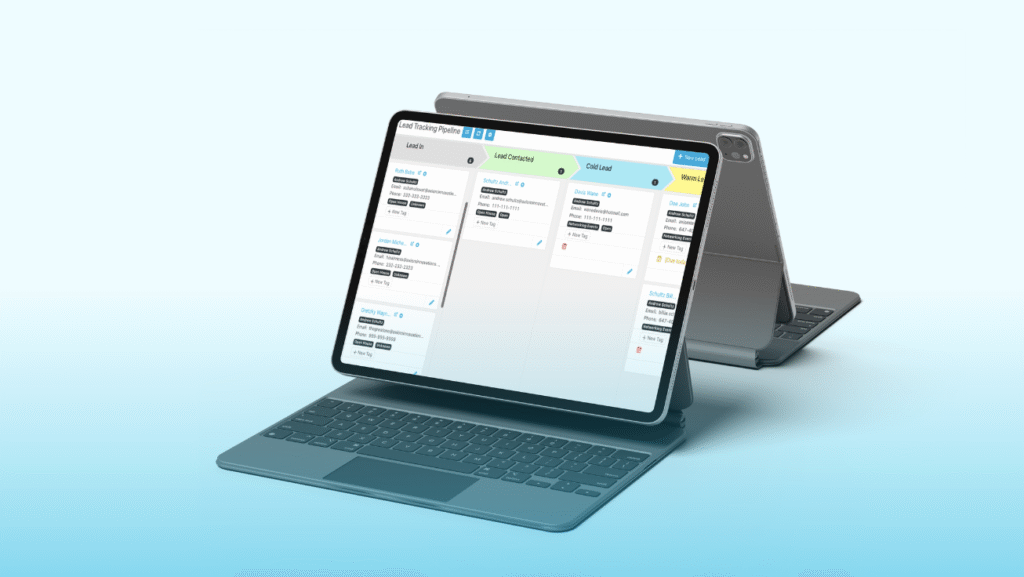
The broker channel isn’t just holding its ground, it’s growing, and the reasons clients give for choosing a broker are shifting toward exactly the kind of advice-led relationship that keeps them coming back. Layer the largest renewal year on record on top of that, plus a regulatory change that’s made switching genuinely easier for most homeowners, and 2026 has the makings of a strong year for brokers who reach out first. If your CRM isn’t already tagging clients by renewal date and triggering that outreach automatically, that’s the first fix worth making before the fall renewal season picks up.
Sources
- Mortgage Professionals Canada, 2026 Consumer Research Report, “The Broker Advantage: How Canadians Are Navigating Mortgage Choices in a More Complex Market,” released July 24, 2026.
- Office of the Superintendent of Financial Institutions (OSFI), Guideline B-20, straight-switch stress test exemption effective November 21, 2024.
- Canadian Real Estate Association (CREA), Monthly Housing Market Report, released August 18, 2026 (July 2026 data).
- Canada Mortgage and Housing Corporation (CMHC), Residential Mortgage Industry Report, Spring 2026 edition.
- Bank of Canada, Monetary Policy Decision, September 2, 2026.